Investing · 🇮🇳 India
Home Loan Prepayment vs SIP: Where Should Your Extra Money Go?
Researched from official sources and fact-checked before publication · How we verify
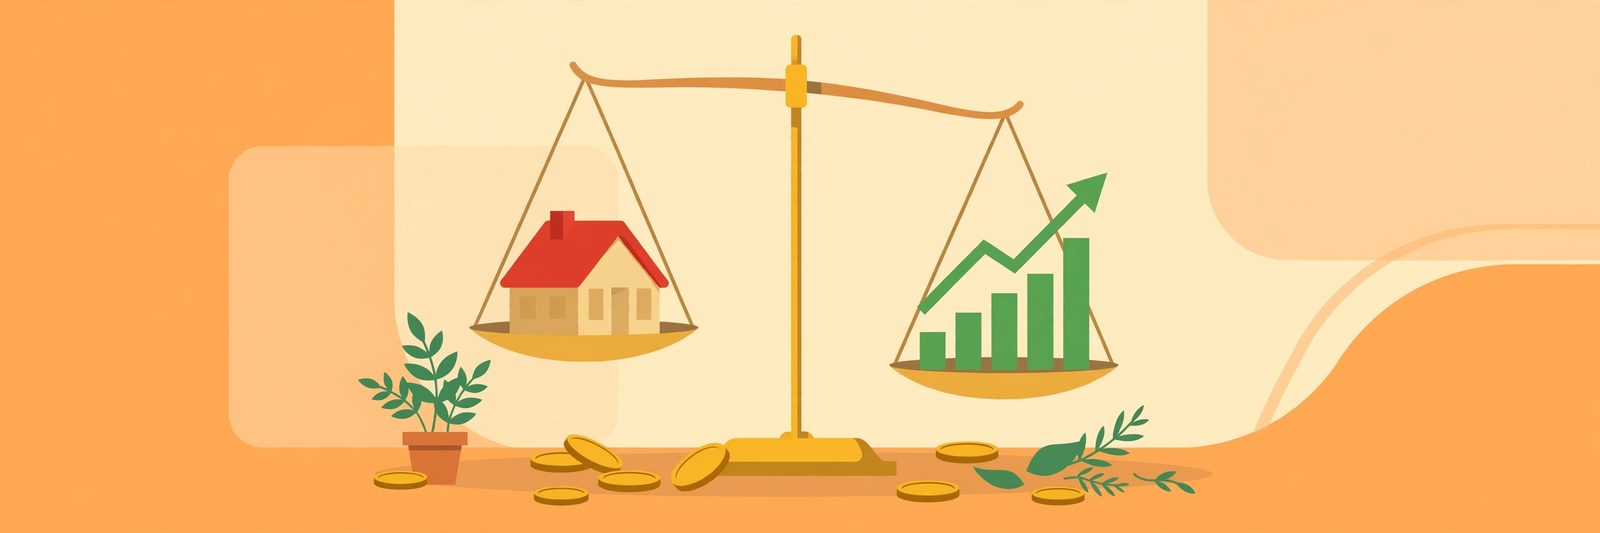
Last April, my friend Nikhil got a salary hike that freed up exactly ₹10,000 a month. By dinner, two people had given him completely opposite advice. His father said, "Extra money means one thing — kill the home loan, you will sleep better." His college friend laughed: "Are you mad? Start a SIP, the market gives 12%." Both sounded completely sure; neither had run a single number. Nikhil's dilemma is the oldest question in Indian personal finance — home loan prepayment vs SIP — so let me run his own loan both ways and see who wins.
His loan is the most common kind in India: ₹50 lakh at 9% for 20 years. Every calculation below uses that one loan and that one extra ₹10,000, no cherry-picked examples, no assumptions that change halfway. If "should I prepay my home loan or invest in SIP" is the question in your head too, stay. And if the word SIP itself is new to you, start with our beginner's guide to what a SIP is, then come back.
Home Loan Prepayment vs SIP: The Same ₹10,000, Run Both Ways
First, the loan as it stands
₹50 lakh at 9% for 20 years means an EMI of about ₹44,986, and total repayment of roughly ₹1.08 crore. That is the ₹50 lakh you borrowed plus around ₹58 lakh in interest. Read that again: the interest nearly equals the loan itself. This is why the extra ₹10,000 matters. In the early years almost everything you pay is interest, and extra money paid towards the principal (the loan amount itself, separate from the interest) attacks exactly that.
Route 1: throw the ₹10,000 at the loan
Nikhil pays ₹54,986 a month instead of ₹44,986, the same EMI plus ₹10,000 towards principal. The loan dies in about 12 years and 10 months instead of 20, over seven years early. Total interest falls from around ₹58 lakh to roughly ₹34 lakh: he saves approximately ₹24 lakh, and once those 12 years and 10 months are done, the entire ₹54,986 a month is his again. The catch: every prepaid rupee is locked inside the house — you cannot withdraw it for a hospital bill or a job gap.
Route 2: the ₹10,000 goes into a SIP
Now the loan runs its full 20 years, and the ₹10,000 goes into an equity mutual fund SIP instead. Here I have to be completely honest about one assumption: if — and it is a real if — the SIP earns an average of 12% a year, ₹10,000 a month grows to about ₹99 lakh in 20 years, on ₹24 lakh actually invested. Equity returns are not guaranteed and never arrive in a smooth line.
You still paid the full ₹58 lakh of interest in this route. And the ₹99 lakh is before tax: the gains (roughly ₹75 lakh here) face equity long-term capital gains tax — currently 12.5% above ₹1.25 lakh a year.
Route 1 has a comeback, though: once the loan ends around year 13, the freed ₹54,986 a month can be invested too, and at the same assumed 12% it reaches roughly ₹74 lakh by year 20. It is still behind the SIP, because the SIP's money compounded longer. On pure maths the SIP wins; whether it wins for you is a different question.
Prepayment vs SIP at a Glance: The Full Side-by-Side
| Question | Prepay the home loan | Invest in a SIP |
|---|---|---|
| What the extra ₹10,000 does | Cuts principal every month, so less interest is charged on every future EMI | Buys mutual fund units every month, compounding over 20 years |
| The "return" you earn | Exactly your loan rate — 9% here — guaranteed and tax-free, since saved interest is never taxed | Whatever the market delivers; assumed 12% here, could be more, could be much less |
| Liquidity | Poor. The money is inside the house; getting it back means selling or re-borrowing | Good. Units can be sold back and money reaches your bank in a few days (tax and a possible early-exit fee aside) |
| Risk | None on the saving itself; the interest saved is certain | Market risk; your corpus (everything the investment has grown to) can fall sharply in a bad year |
| Tax angle | Shrinks your future interest, so it also shrinks your Section 24(b) deduction (old regime) | Equity gains taxed at exit: 12.5% long-term capital gains tax above ₹1.25 lakh of gains per financial year |
| Peace of mind | High for most people: debt visibly shrinking is a powerful feeling | Lower in falling markets; watching a corpus drop tests your nerve |
You are choosing which risk you would rather live with.
The Break-Even Rate: Your Loan Rate Decides Most of This
Every home loan prepay vs invest argument reduces to one comparison: your loan rate versus what your money can earn after tax. A prepaid rupee "earns" the loan rate, risk-free. A SIP rupee must beat that rate — after tax, after bad years — to justify itself:
| Your home loan rate | What the maths usually says | Why |
|---|---|---|
| Below ~8.5% | SIP usually wins | A modest long-term equity return clears a cheap loan's cost comfortably |
| Around 9–9.5% | A genuine toss-up | The gap is thin; tax, behaviour and job security decide |
| Above ~9.5–10% | Prepayment usually wins | A guaranteed double-digit saving is very hard for any investment to beat reliably |
Nikhil, at exactly 9%, sits in the toss-up zone, which is why both his father and his friend could sound right. Most home loans are floating-rate (the rate moves up and down with the market), so revisit this when your rate changes by about 1% or more.
The Quiet Tax Angle: Section 24(b)
Here is the part nobody mentions at the dinner table. Under Section 24(b) of the Income Tax Act, if you file under the old regime, interest on a home loan for a house you live in is deductible up to ₹2 lakh a year. At the 30% slab, that saves up to roughly ₹60,000 of tax a year, on the slice of interest inside that limit, your loan is not really costing you 9%; the tax department refunds part of it.
Now the twist: prepayment shrinks your interest, and so shrinks the deduction. If you prepay aggressively while part of your ₹2 lakh deduction is still unused, you give up a tax subsidy, just to save interest that the tax department was partly paying for anyway. That does not make prepayment wrong: in our example, the first year's interest alone is around ₹4.4 lakh, far above the ₹2 lakh cap. But if your yearly interest is near or below ₹2 lakh and you are in a high slab, the SIP's case strengthens. In the new regime, this deduction is unavailable for a self-occupied home at all.
If You Prepay, Do It Properly
Plenty of people prepay badly and leave lakhs on the table. The mechanics matter:
- Choose tenure reduction, not EMI reduction. When you prepay a lump sum, banks often offer to lower your EMI. Refuse politely. Keeping the EMI unchanged and cutting the tenure is what produces the ~₹24 lakh saving above; a smaller EMI stretches the loan back out and gives most of that interest saving back to the bank.
- Check the prepayment charges. On floating-rate home loans taken by individuals, RBI rules say banks cannot charge a prepayment or foreclosure penalty. Fixed-rate loans differ: read your agreement before moving money.
- Never raid the emergency fund to prepay. A smaller loan does not help in an emergency. Keep six months of expenses aside first. If yours is not built yet, our emergency fund guide is the step before this one.
- Treat it as an "extra EMI" habit. The extra EMI vs SIP framing helps: one extra EMI a year, paid like clockwork, shortens a 20-year loan by roughly three and a half years. Small and automatic beats large and occasional.
The 50-50 Split: Half Prepayment, Half SIP
There is a third door, the one I suggest most often: split the ₹10,000 (₹5,000 to prepayment, ₹5,000 to a SIP). On Nikhil's loan, the extra ₹5,000 closes it in about 15 and a half years with interest of roughly ₹43 lakh, saving around ₹15 lakh. Meanwhile the ₹5,000 SIP, at the same assumed 12%, grows to about ₹49 lakh in 20 years. You get a loan that ends years early, and a liquid corpus growing in the background.
A deliberate compromise: if markets disappoint, you still killed years of interest; if markets fly, you own a piece of that too. It beats what usually happens instead — letting the ₹10,000 dissolve into lifestyle spending while the debate continues.
What the Spreadsheet Cannot See
Now let me argue against my own maths a little. The ₹99 lakh figure assumes an investor who invests every month for 20 years and does nothing foolish in a crash. Real people pause SIPs when markets fall 20%, redeem to "wait for clarity", and return two rallies later. A 12% assumption handled by a panicky investor becomes 7% in real life. Suddenly the boring prepayment was the winner all along.
The reverse trap exists too. Prepayment concentrates everything in one illiquid asset, and the EMI, the real monthly risk, stays unchanged until the loan is nearly done. Lose your job in year 3 of the SIP route and you can pause the SIP, even sell some units. In the prepay route the bank still wants ₹44,986 on the due date, and your extra payments are locked in the walls. Neither route is truly safe. Each one just protects you from a different kind of trouble.
And some people are simply not built to owe money. If a loan balance sits in your chest like a stone, watching it shrink has a value no table captures — "you will sleep better" is not a financial argument, but sleep is not nothing. (Still deciding whether to buy at all? That question comes first — see our rent vs buy analysis.)
Frequently Asked Questions
My loan rate is 9%. Should I prepay my home loan or invest in SIP?
At exactly 9%, neither side wins by default. If you are young, securely employed, calm when markets fall, and claiming the old regime's Section 24(b) deduction, the SIP has the stronger mathematical case. If your income is uneven, or you know you would panic and sell in a fall, prepay — or split 50-50, which most people in this range end up happiest with.
Is it better to reduce the EMI or the tenure when I prepay?
Choose tenure, almost always. Keeping the EMI unchanged is where the big interest saving comes from. Reducing the EMI improves cash flow, but it stretches the loan out again and the saving shrinks. Take the EMI cut only if your budget genuinely cannot carry the current EMI.
Are there charges for prepaying a home loan in India?
For floating-rate loans taken by individual borrowers, RBI rules prohibit prepayment or foreclosure penalties. Fixed-rate loans may carry charges. Check your sanction letter before a large prepayment.
Does prepaying reduce my tax benefits?
Yes, under the old regime. Prepayment lowers the loan, so yearly interest falls, and with it the Section 24(b) deduction (on up to ₹2 lakh of interest a year) and eventually the principal's share of Section 80C. In the new regime these deductions are unavailable on a self-occupied home anyway.
Is paying one extra EMI a year better than a SIP?
They do different jobs. One extra EMI a year cuts roughly three and a half years off a 20-year loan, a guaranteed saving at your loan rate. Putting the same money into a SIP could grow more, but the market decides. If your loan rate is high, the extra EMI is the safer win; if it is low, the SIP usually has the edge.
Key Takeaways
- On a ₹50 lakh loan at 9% for 20 years, you pay roughly ₹58 lakh in interest, which is why the extra ₹10,000 matters so much.
- Prepaying closes the loan in about 13 years and saves ~₹24 lakh of interest, guaranteed, but it locks the money in the house.
- The same ₹10,000 in a SIP could reach roughly ₹99 lakh in 20 years at an assumed 12% (an illustration, not a promise) while the loan runs its full term.
- Break-even sits near your loan rate: below ~8.5% the SIP usually wins on maths, above ~9.5–10% prepayment usually wins, in between it is a toss-up.
- Section 24(b) subsidises your loan under the old regime — if you prepay while part of that deduction is still unused, you waste the subsidy.
- Pick tenure reduction over EMI reduction, protect the emergency fund, and clear costlier debt first.
- The 50-50 split is a respectable answer: it saves ~₹15 lakh of interest and still builds a ~₹49 lakh corpus.
Final Thoughts
Nikhil, in the end, split it. ₹5,000 went to the loan, ₹5,000 to a SIP, and both camps declared partial victory. I think he chose well — not because 50-50 is magic, but because it matched his 9% rate, where the maths gives no clear winner, and it matched the man himself: steady, not fearless, with a young family that needs some money within reach. The real answer: run your own rate through the break-even table, be honest about the investor you actually are, and pick the plan you will still be following in year 10. Trust your own numbers over any article, including this one — the rate on your sanction letter matters more than anybody's opinion at a dinner table. A decent plan you keep beats a perfect plan you abandon.
Disclaimer: This article is for educational purposes only and is not financial advice. Please do your own research or consult a qualified financial advisor before making investment decisions.
Continue Reading
NPS can beat PPF on returns but locks your money till 60 and taxes the annuity. PPF is tax-free and flexible but slower. Here's the full comparison — and when 'both' is the right answer.
From your first demat account to your first share: a beginner's walkthrough of the Indian stock market, with the rules and mistakes that actually matter.
PPF gives you safe, tax-free ~7.1% returns with a 15-year lock-in. Mutual funds offer higher growth potential with market risk. Here's how to decide — including doing both.