Tax Planning · 🇮🇳 India
ELSS vs PPF vs NPS in 2026: Which Tax-Saver Wins in the New Tax Regime?
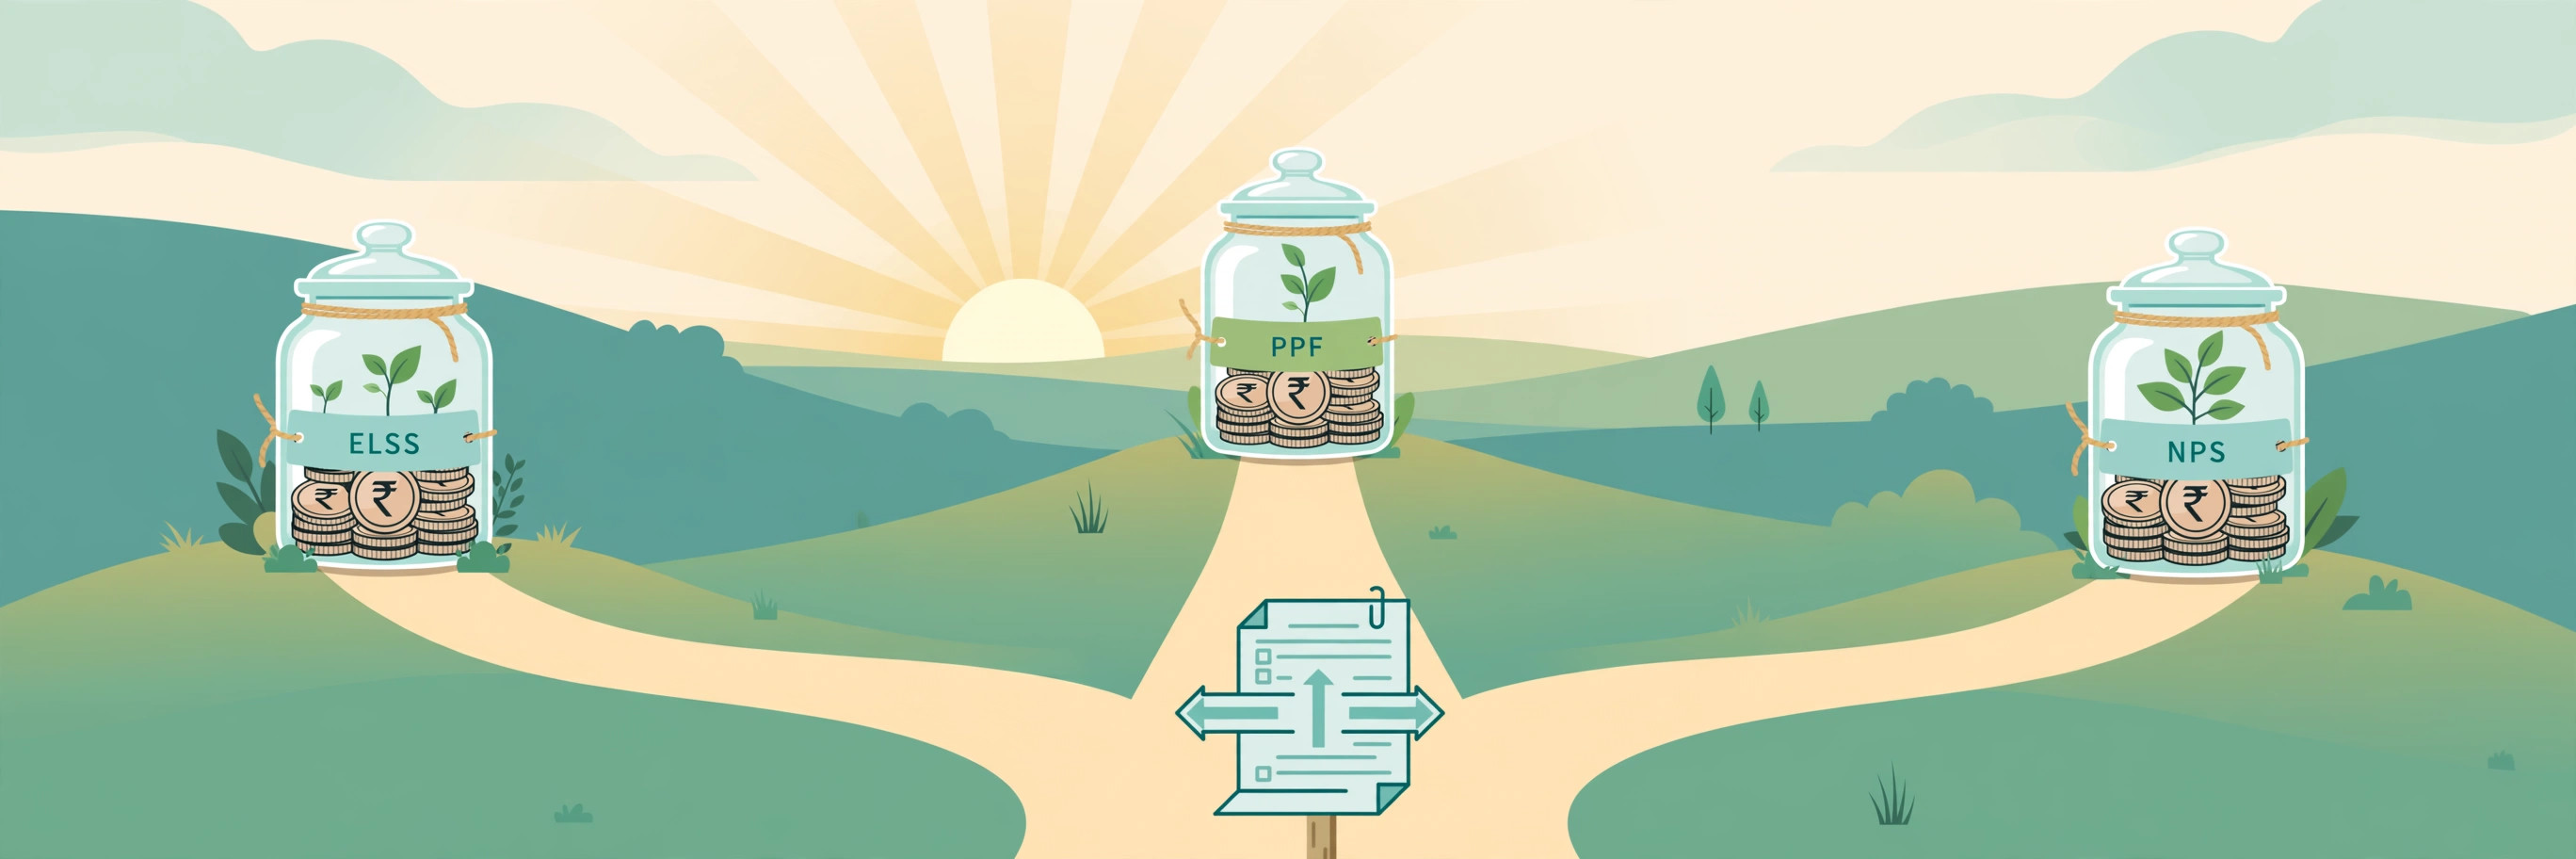
A colleague of mine, Sana, sent me three screenshots one evening: an ELSS fund page, her PPF passbook, and the NPS statement her employer had opened for her. Her question was short and very Indian: “All three save tax. All three are ‘best’. Which one do I put ₹1.5 lakh in?” I liked the question because it hides a trap. In 2026, the first answer is not ELSS, PPF or NPS. The first answer is your tax regime. Pick the regime wrong, and the “tax-saver” may save no tax at all.
The three are not brands of the same soap. ELSS (Equity Linked Savings Scheme) is an equity mutual fund with a three-year lock-in on every instalment. PPF (Public Provident Fund) is a government small-savings account with a fixed, tax-free return and a 15-year life. NPS (National Pension System) is a retirement account, invested across market-linked assets and built to stay locked until age 60. One offers flexibility plus equity growth, one offers certainty, and one stops you raiding retirement money when life gets noisy. Below, I compare them in the order a real person should think: regime first, product second, returns third — using the new Income Tax Act, 2025 section numbers alongside the names we all remember, like Section 123 (the old Section 80C).
Tax rules, section references and the PPF rate in this guide were checked as of October 2026. Small-savings rates are revised periodically and tax provisions can change with a Finance Act — verify the current position on the official sources linked below before investing or filing.
Start With the Regime, Not the Product
The new regime is the default under Section 202, the new-regime provision of the Income Tax Act, 2025. Its bargain is simple: lower slab rates and a large rebate, but very few deductions. With Section 156 (the old Section 87A), tax can be zero on taxable income up to ₹12 lakh — and for a salaried person, the standard deduction can make salary up to about ₹12.75 lakh tax-free. If that is you, no product can “save tax” for you. Your tax is already zero before the product enters the room.
The old regime keeps the deduction cupboard stocked. The big shared pool is Section 123 (the old Section 80C): up to ₹1.5 lakh across EPF, PPF, ELSS, insurance premiums, home-loan principal and your own NPS Tier I contribution within the prescribed limits. NPS also sits in Section 124 (the old Section 80CCD), which is where the familiar extra ₹50,000 old-regime deduction for your own NPS contribution, over and above the Section 123 pool, comes from. None of this applies in the new regime. ELSS does not become deductible because it is an equity fund, PPF does not become deductible because it is safe, and self-funded NPS does not become deductible because it is virtuous.
One bridge connects the two worlds: employer NPS contribution. If your employer contributes to NPS as part of your salary structure, that contribution can be deductible under the Section 124 family — the old 80CCD(2) route — in both regimes, up to 14% of Basic + DA with effect from 1 April 2026. (Basic + DA means basic salary plus dearness allowance, where DA applies.) This is not the same as depositing your own money. If your CTC offers employer NPS, do not wave it away with “NPS has no benefit in the new regime.” That sentence is true only for your own deposit.
Not settled on old versus new yet? Pause here and work through our new vs old tax regime guide first. Ten minutes there can save you from buying a deduction you cannot claim.
The Three Contenders in Plain English
ELSS: equity growth, shortest lock-in
ELSS funds live in the mutual-fund world overseen by SEBI, with investor education from AMFI. The charm is the lock-in: three years, the shortest of the classic tax-savers. The catch hides in one word — “each”. Every SIP instalment carries its own three-year clock, so the first instalment frees up years before the last. Returns are market-linked: you are not buying a rate, you are buying equity exposure with a tax wrapper in the old regime. Model your own numbers on the ELSS calculator. I like ELSS when the goal is five-plus years away and the investor can watch a sharp fall without doing something emotional at midnight.
PPF: the slow, tax-free tortoise
PPF is not exciting, and that is the point. The rate used in this article is 7.1%; small-savings rates are announced by the government, so check the Department of Economic Affairs when you read this later. PPF’s superpower is EEE treatment: deposits can earn a deduction in the old regime, interest is tax-free, and maturity is tax-free. Even in the new regime, where the deposit earns no deduction, that tax-free return keeps PPF relevant as the debt side of a portfolio. The account runs 15 years, deposits are capped at ₹1.5 lakh a year, and partial withdrawals are allowed from the seventh year under the scheme rules — locked, but not sealed in concrete. Run a full 15- or 20-year projection on the PPF calculator.
NPS: the retirement room with a strong door
NPS is regulated by the PFRDA, with accounts serviced through the CRA system (the NSDL e-Governance business is now Protean; its CRA site is npscra.nsdl.co.in). Your money is invested across equity, corporate bonds and government securities in the allocation you choose, so the corpus can outgrow PPF over long periods — and can also fall in a bad stretch. The door is both the feature and the complaint: Tier I money stays locked until 60, with only limited partial withdrawals for specified needs. At exit, up to 60% of the corpus can be withdrawn tax-free, while at least 40% buys an annuity (a pension product) whose payouts are taxed as income. For the two-way retirement fight, see our NPS vs PPF comparison; test contribution illustrations on the NPS calculator.
ELSS vs PPF vs NPS: The Full Comparison
| Feature | ELSS | PPF | NPS (Tier I) |
|---|---|---|---|
| Main job | Equity growth with the shortest tax-saver lock-in | Guaranteed, tax-free debt savings | Dedicated retirement corpus |
| Lock-in | 3 years on each investment/instalment | 15-year account; partial withdrawal from year 7 under scheme rules | Mainly till age 60; limited partial withdrawals only for specified purposes |
| Returns | Market-linked equity; no promised rate (examples below assume 12% a year, for illustration only) | 7.1% used here; government rates are revised periodically | Market-linked across equity, corporate bonds and government securities (examples assume 10% a year, for illustration only) |
| Risk | Highest of the three; value can fall in the short term | Sovereign-backed small-savings scheme; lowest risk of the three | Market risk depends on your allocation; the equity portion can fall |
| Tax when you invest — old regime | Deduction within the shared ₹1.5 lakh Section 123 (old 80C) pool | Deduction within the shared ₹1.5 lakh Section 123 (old 80C) pool | Own contribution sits in the Section 123 / Section 124 framework, with the extra ₹50,000 old-regime NPS deduction above the ₹1.5 lakh pool; employer contribution has its own route |
| Tax when you invest — new regime | No deduction | No deduction | No deduction for your own deposit; employer contribution can still be deductible up to 14% of Basic + DA under the Section 124 employer route |
| Tax while money grows | No tax inside the fund each year; tax falls mainly on redemption | Interest is tax-free | No tax on growth inside the account each year |
| Tax at exit | Equity long-term capital gains taxed at 12.5% above ₹1.25 lakh of gains in a financial year | Maturity is tax-free | Up to 60% lump sum tax-free; at least 40% buys an annuity, and the pension is taxed as income when received |
| Minimums | No single statutory minimum; the fund house sets SIP/lumpsum minimums in the scheme documents | ₹500 minimum deposit in a financial year | Small minimum contributions apply; check the current CRA/PFRDA schedule before opening, as servicing rules change |
| Maximum that matters | You can invest more, but old-regime deduction is capped by the shared Section 123 pool | Deposits capped at ₹1.5 lakh per financial year | No ₹1.5 lakh deposit cap for investing; deduction limits are a separate question |
| Best for | Goals 5+ years away; investors who can tolerate equity swings | Safe core savings and money that should not dance with the market | Retirement-only money, employer NPS contribution, investors who want a hard lock-in |
Tax references: Income Tax Department. PPF rates: Department of Economic Affairs. NPS structure: PFRDA and CRA material. Mutual funds: SEBI and AMFI investor resources.
Read the table row by row and a pattern emerges. ELSS wins on flexibility, but asks your stomach to participate. PPF gives up speed for a clean, tax-free finish. NPS is not really competing for your five-year goal at all — it guards the money your 60-year-old self will need. The “winner” depends on which job you are hiring for.
What ₹1.5 Lakh a Year Could Become
Now the numbers, with assumptions in daylight. You invest ₹1.5 lakh at the start of every year. PPF compounds at 7.1%. ELSS is assumed to earn 12% a year and NPS 10% — smooth, imaginary lines chosen only to compare the mechanics. Real market returns arrive in lumps, with bad years mixed in, and past performance does not guarantee future returns. Fees and future tax changes are ignored. For ELSS, I assume you redeem everything in one financial year after the full period and pay 12.5% long-term capital gains tax on gains above ₹1.25 lakh.
| Horizon | Total invested | ELSS after estimated one-shot LTCG tax | PPF value (tax-free) | NPS corpus and exit shape |
|---|---|---|---|---|
| 15 years | ₹22.50 lakh | ₹62.63 lakh before tax; about ₹57.77 lakh after estimated tax of ₹4.86 lakh | About ₹40.68 lakh; no tax on interest or maturity | About ₹52.42 lakh before exit treatment; roughly ₹31.45 lakh is the 60% tax-free lump-sum portion and ₹20.97 lakh the 40% annuity portion, whose pension is taxed later |
| 20 years | ₹30.00 lakh | ₹1.21 crore before tax; about ₹1.10 crore after estimated tax of ₹11.22 lakh | About ₹66.58 lakh; no tax on interest or maturity | About ₹94.50 lakh before exit treatment; roughly ₹56.70 lakh is the 60% tax-free lump-sum portion and ₹37.80 lakh the 40% annuity portion, whose pension is taxed later |
ELSS is the sprinter: the highest ending value even after a visible tax bill. Two warnings, though. If you redeem across more than one financial year, the ₹1.25 lakh annual gains exemption applies in each year, so real tax may be lower than this one-shot estimate. And if markets fall near your goal, the pre-tax number itself shrinks. A spreadsheet can assume 12%; the market has not signed it.
PPF looks sleepy until you remember the ending value is tax-free and the path is calm. For money meant for a home deposit in year 16 or a child’s education buffer, calm has value. Not every rupee must chase the highest return — some rupees have the job of simply being there. NPS sits between the two here, but its exit shape differs: the 40% annuity portion is not lost, it becomes pension income. What you cannot do is treat the full NPS corpus as spendable cash at 60.
Post-Tax Reality: Two Readers, Two Answers
Meera files under the new regime. Her salary sits below the level where tax bites after the standard deduction and the Section 156 rebate, so she gets no deduction from any of the three. For her, “tax-saver” is marketing fog. ELSS must justify itself as an equity investment for a distant goal; PPF still works because its return is tax-free; NPS needs the employer contribution or a genuine retirement reason, because the lock-in till 60 is a high price for a deduction that does not exist.
Arjun files under the old regime. His EPF already uses ₹92,000 of the Section 123 pool, leaving only ₹58,000 of room. If he blindly puts another ₹1.5 lakh into ELSS “for tax”, only part of it adds any deduction; the rest is simply an equity investment. That may be fine — but he should know which part is tax planning and which part is investing. Always add up EPF, premiums, tuition fees and home-loan principal before buying a fresh tax-saver. And the deduction is worth real money when it applies: at a 30% marginal rate, a full ₹1.5 lakh deduction cuts tax by roughly ₹45,000 before cess and surcharge. It is a reason to choose well — never a reason to choose badly.
Who Should Pick What in 2026?
Salary around ₹12.75 lakh or less, new regime, tax already zero
Start with the goal, not tax. ELSS can serve as an equity fund for distant goals, but compare it honestly with other equity options instead of worshipping the lock-in. PPF remains clean and tax-free for safe money. Say yes to NPS mainly when your employer contributes, or when you deliberately want a retirement account you cannot raid.
Old regime, higher slab, Section 123 room still unused
ELSS is my default first candidate for the growth portion: it uses the same pool as PPF, offers equity return potential, and frees each instalment after three years. The condition is temperament — if a market fall makes you stop SIPs, the theoretical return will not rescue you.
Risk-averse, or building the debt side of the plan
PPF is the clean answer: a government small-savings return, tax-free at every stage. I would rather see a nervous investor hold PPF peacefully for 15 years than buy ELSS, panic in year two, and exit at the first unlock after a fall. Suitability beats bravado.
Employer offers NPS contribution
Take it seriously in both regimes. Employer contribution up to 14% of Basic + DA can be deductible under the Section 124 route regardless of your regime choice for personal deductions. If restructuring salary towards employer NPS changes take-home or other benefits, compare the full CTC — but the outdated line “NPS is useless in the new regime” is wrong for employer money.
Under 40, and the money is only for retirement
NPS becomes much more attractive. The lock-in hurts less when retirement is the actual goal and the money is not needed for a home, a business or an emergency. Pair it with PPF for stability or ELSS for a flexible equity bucket — our NPS vs PPF guide goes deeper on this retirement-only choice.
You may need the money before 60, or you have no employer NPS
Be careful with NPS. A product can be excellent and still wrong for a particular rupee: for a house in eight years or a career break in five, its door is too strong. Freelancers and founders get no employer contribution to rescue NPS in the new regime either — there, it must win purely as a retirement product, or not at all.
Most people, honestly, need a split rather than a winner: ELSS for growth, PPF for certainty, NPS for retirement and employer money. If you cannot explain in one sentence why a product sits in your portfolio, it is probably there because of a deadline, a headline or a salesperson.
Sources and Where to Verify
- Income Tax Department — regime provisions, deductions and rebate rules.
- Department of Economic Affairs — small-savings rate notifications, including PPF.
- PFRDA — NPS regulations and the exit/withdrawal framework.
- Protean/NSDL NPS CRA — NPS account servicing and subscriber information.
- SEBI and AMFI — mutual fund regulation and investor education for ELSS.
Frequently Asked Questions
ELSS vs PPF vs NPS: which is better in the new tax regime?
For deduction, none of them — ELSS, PPF and self-funded NPS give no deduction in the new regime. Choose by goal: ELSS for equity growth with a three-year lock-in per instalment, PPF for tax-free guaranteed savings over 15 years, NPS for retirement money locked till 60. Employer NPS contribution is the exception and can still be deductible in both regimes.
Can I invest in all three in the same year?
Yes, many people do. Just respect the deduction maths: in the old regime, ELSS, PPF and your own NPS contributions largely share the Section 123 (old 80C) ceiling, apart from the specific old-regime NPS extra and the separate employer route. Investing in all three is fine; expecting three separate ₹1.5 lakh deductions is not.
Does PPF still make sense with no deduction in the new regime?
It can. PPF’s new-regime case is not the entry deduction but the tax-free interest and tax-free maturity on a government small-savings account. If you need a safe debt allocation and accept the 15-year structure, it fits. If you need the money soon, the lock-in — not the tax — is the problem.
Is NPS worth it without an employer contribution?
Sometimes. In the old regime, the extra NPS deduction helps once the Section 123 pool is full. In the new regime, NPS must win as a retirement product — long lock-in, market-linked growth, annuity at exit. If you dislike the till-60 lock or need flexibility, that rupee may belong in ELSS or PPF instead.
Why is the ELSS post-tax figure lower than the 12% illustration?
Because 12% is only an assumed pre-tax return. Real returns vary, and on redemption, equity long-term capital gains are taxed at 12.5% above ₹1.25 lakh of gains in a financial year. The example assumes a one-shot redemption; spreading redemptions across years may reduce tax, since the annual exemption can apply each year.
What should I check before choosing the old regime just for these three?
Add up everything the old regime lets you claim — EPF, PPF, ELSS, premiums, HRA, home-loan benefits, tuition fees, NPS — then compare total tax under both regimes. A deduction helps only if the old regime’s final tax is actually lower. Our regime comparison walks through that calculation.
Which one should a beginner start with?
Start with the goal and regime, not the product name. Old regime, long horizon, unused Section 123 room? ELSS by SIP is a simple start. Cannot tolerate falls? PPF. Employer contributing to NPS? Understand that benefit before opting out. Small, regular and understood beats large, rushed and copied.
Key Takeaways
- In the new regime, ELSS, PPF and self-funded NPS give no deduction — buy them only if the investment case stands on its own.
- Employer NPS contribution is different: deductible in both regimes, up to 14% of Basic + DA under the Section 124 employer route.
- Section 123 (the old Section 80C) is one shared ₹1.5 lakh pool in the old regime — not a fresh pool per product.
- ELSS offers equity growth and a three-year lock-in per instalment, with gains taxed at 12.5% above ₹1.25 lakh in a financial year.
- PPF is slower but tax-free at every stage, with a 15-year account and a ₹1.5 lakh annual deposit cap.
- NPS means retirement discipline: market-linked growth, a hard lock-in till 60, a tax-free lump-sum portion at exit and taxable pension from the annuity portion.
- For most savers the best answer is a split — ELSS for growth, PPF for certainty, NPS for retirement and employer money — decided after the regime question.
The Bottom Line
So, which tax-saver wins in the new tax regime? Honestly, the phrase needs retiring. In the new regime these are not tax-savers at all — they are investments with different locks, risks and exit taxes. ELSS is the flexible equity runner, PPF the tax-free tortoise, NPS the retirement vault, strongest when an employer is also paying in. In the old regime, the deduction can still change the ranking — but only after you check how much Section 123 room is genuinely left.
Sana’s answer was boring in the best way: employer NPS stayed, PPF took the safe portion, and ELSS took the long-term growth money she could leave alone. No single winner — just three tools, finally doing three different jobs.
Disclaimer: This article is for educational purposes only and is not financial, tax or investment advice. Tax provisions, section references, scheme rules and interest rates can change; verify them on official sources or consult a qualified tax professional or financial adviser before acting. CashCrafty and the author are not SEBI-registered investment advisers. Mutual fund investments are subject to market risks; read all scheme documents carefully.
Continue Reading
From your first demat account to your first share: a beginner's walkthrough of the Indian stock market, with the rules and mistakes that actually matter.
An emergency fund is money set aside for life's surprises — job loss, medical bills, urgent repairs. This guide shows you how much to save, where to keep it, and how to build it step by step.
A 3-digit number decides your loan interest rate — or whether you get the loan at all. Here's what a CIBIL score really is, the 5 factors behind it, and how to push yours above 750.