Budgeting · 🇮🇳 India
The 50/30/20 Budgeting Rule, Explained for Indian Households
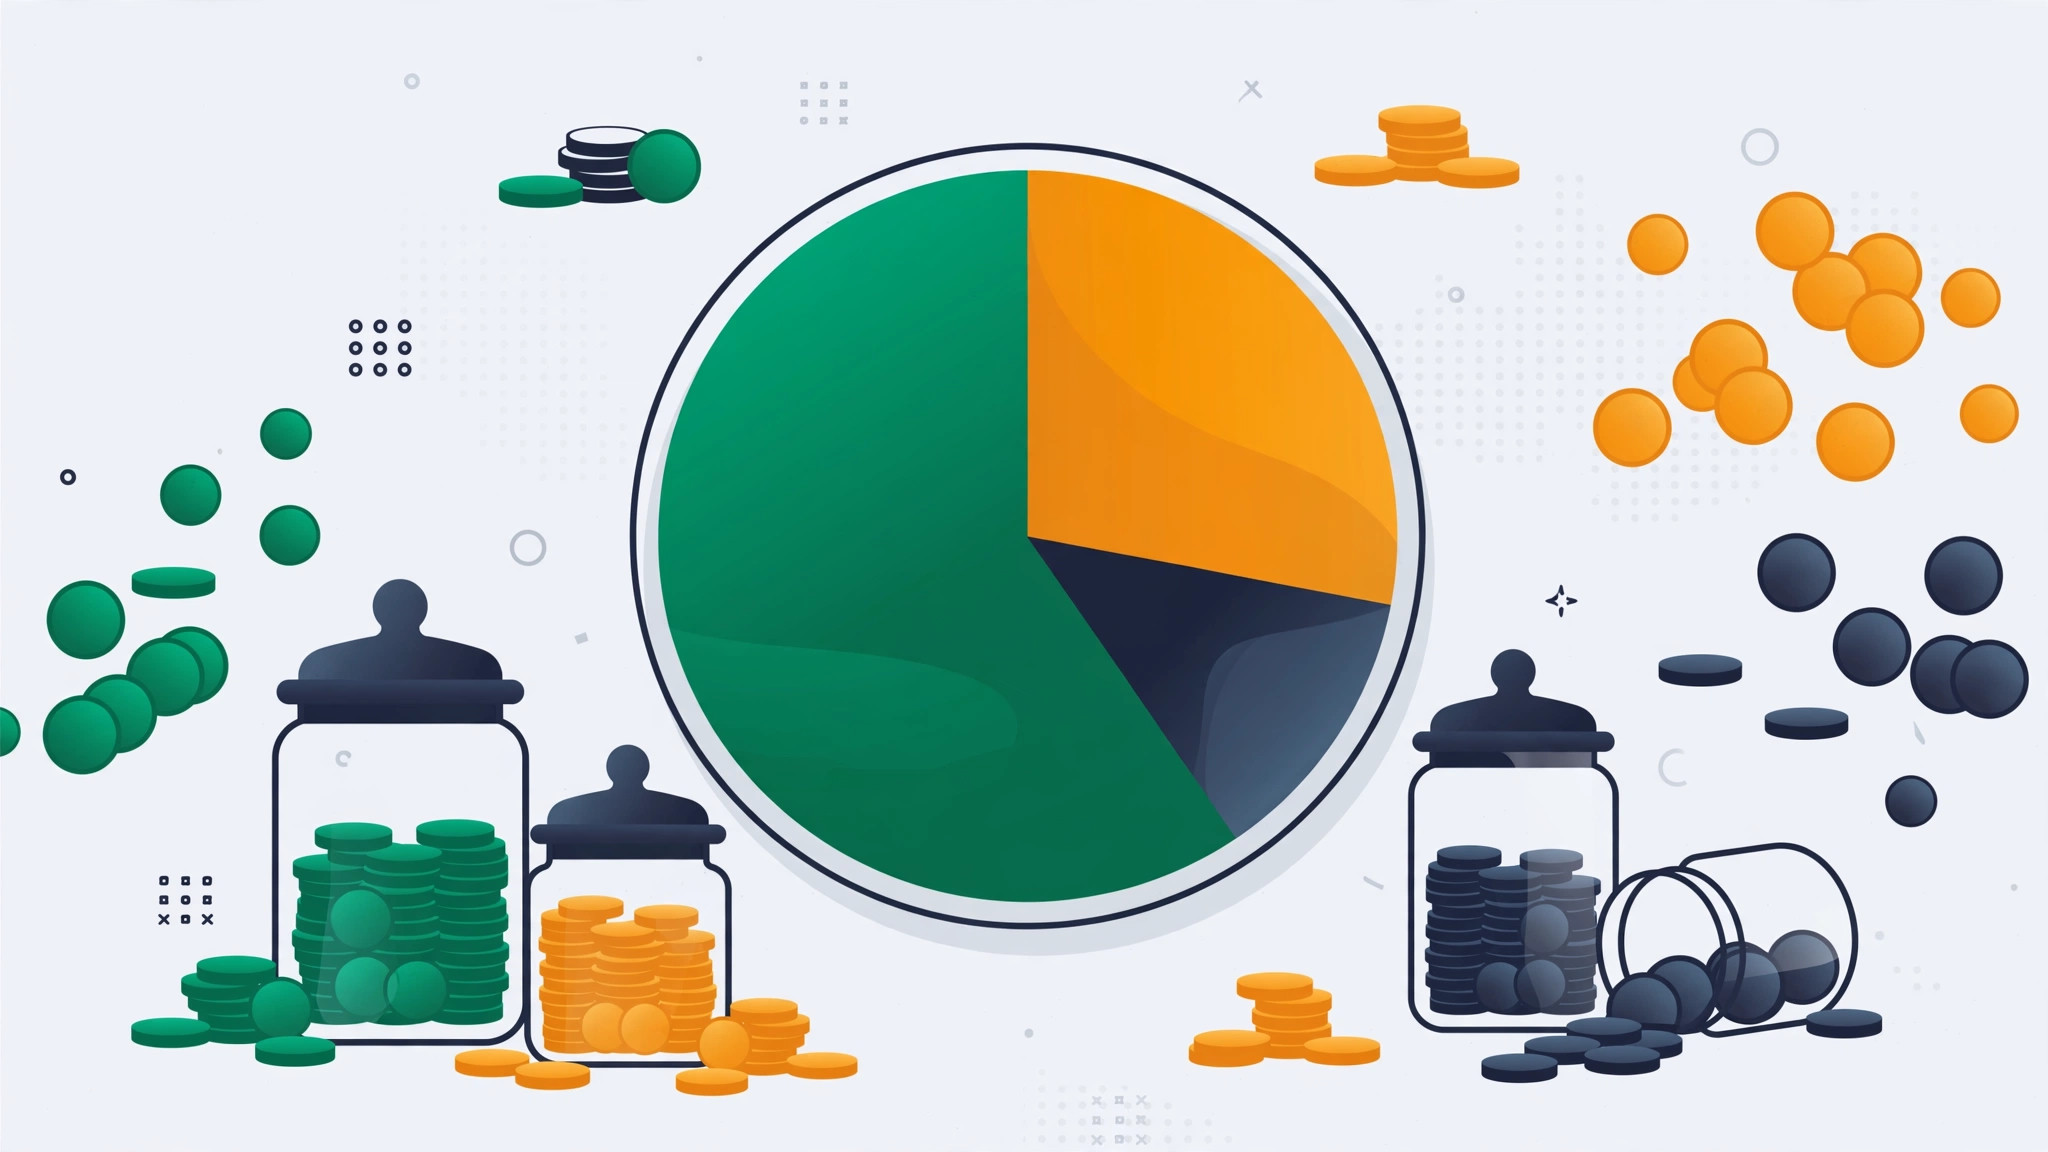
I remember the first time I heard about the 50/30/20 rule. I was 24, earning my first proper salary, and my money was doing something mysterious at the end of every month — vanishing. A friend explained the rule in about thirty seconds: half your income for needs, 30% for wants, 20% for the future. I laughed. "My rent alone is half my salary." And that's exactly why this rule is worth talking about properly — especially for Indian households, where it needs some practical tweaking.
The 50/30/20 rule was popularised by US Senator Elizabeth Warren and her daughter Amelia Warren Tyagi in their 2005 book All Your Worth: The Ultimate Lifetime Money Plan. It's a budgeting framework, not a law of physics: spend roughly 50% of your after-tax income on needs, 30% on wants, and put 20% toward savings and debt repayment. Simple enough to remember, which is its real superpower. But imported straight from America, it bumps into Indian realities — metro rents, family obligations, EMIs. So let's break it down, adapt it, and build a real budget with it.
The Rule in 60 Seconds
Take your in-hand monthly income — the money that actually lands in your account after tax, PF and professional tax deductions. Not your CTC, not your gross. Your in-hand.
- 50% — Needs: the non-negotiables. Rent, groceries, utilities, transport to work, insurance premiums, minimum loan payments, kids' school fees.
- 30% — Wants: the good life. Eating out, streaming subscriptions, shopping, travel, hobbies, that café coffee.
- 20% — Savings & debt: your future self's share. Emergency fund, SIPs, PPF, extra EMI payments beyond the minimum, NPS contributions.
That's it. The whole philosophy is that budgeting shouldn't require a spreadsheet PhD. If your spending roughly matches these buckets, you're in decent shape.
A Worked Example: ₹60,000 In-Hand
Let's make this real. Say you earn ₹60,000 a month in hand, living in a metro city. Here's what textbook 50/30/20 looks like:
- Needs (₹30,000): rent ₹15,000 (shared flat or 1BHK in a non-prime area), groceries ₹7,000, utilities + phone + internet ₹2,500, commute ₹3,000, health insurance premium share ₹1,500, misc essentials ₹1,000.
- Wants (₹18,000): eating out and ordering in ₹5,000, shopping and clothes ₹5,000, subscriptions and entertainment ₹1,500, weekend outings ₹4,000, personal care and misc ₹2,500.
- Savings (₹12,000): emergency fund ₹4,000, equity SIP ₹5,000, PPF ₹3,000.
Looks tidy on paper, right? Now, my take: for a lot of Indians, this exact split is aspirational fiction. And that's fine — the rule is a compass, not a cage. Let me show you where it bends.
Where It Bends: Indian Realities Nobody Warns You About
Metro rent eats the 50%
In Mumbai, a modest 1BHK can easily cost ₹25,000–35,000. On a ₹60,000 salary, rent alone blows past the entire needs budget. Does that mean the rule is useless for Mumbaikars? No — it means your real numbers might look like 65/20/15 for a while. The rule's value is in showing you that imbalance clearly, so you can decide: get a roommate, move slightly farther out, or accept a lower savings rate temporarily while you grow your income. Awareness first, optimisation second.
EMIs: the great Indian budget-killer
Here's a nuance most articles skip: where do EMIs go? Minimum loan payments count as needs (you must pay them), but any extra payment toward killing the loan faster counts as savings — because it's building your net worth. A ₹12,000 car EMI on a ₹60,000 salary is a flashing red light regardless of which bucket you file it under, though. If EMIs cross 30–40% of your income, the problem isn't your budget categories — it's the loans.
Family support isn't a "want"
Many of us send money home — parents' expenses, a sibling's fees. Western budgeting articles have no bucket for this, but in India it's often as non-negotiable as rent. Put it in needs, without guilt. Just be realistic about the amount when you do your maths, because pretending it doesn't exist is how budgets quietly die.
Needs vs Wants: The Indian Edition (With Examples)
The trickiest part of this rule isn't the maths — it's honestly classifying your spending. Our brains are excellent lawyers for our wants. The question that clears up about 80% of arguments: "what breaks if I stop?" If nothing breaks, it's a want.
| Spending item | Need or want? | Why |
|---|---|---|
| Basic groceries, cooking gas | Need | Survival basics |
| Zomato/Swiggy 4x a week | Want | Convenience, not survival — be honest |
| Commute to office (metro/bus/fuel) | Need | Required to earn |
| Festival spending (Diwali, etc.) | Want (budgeted) | Predictable — save for it monthly instead of a shock |
| Kids' school fees | Need | Non-negotiable commitment |
| Private tuition classes | Debatable | Need if essential for the child's progress; want if it's keeping-up-with-Sharma-ji |
| OTT + music subscriptions | Want | Even if it feels essential after a long day |
| Term insurance premium | Need | Protection for dependents — non-negotiable if others rely on you |
| Money sent to parents | Need | Family obligation, treat it like rent |
| New phone every year | Want | A working phone is the need; the upgrade is the want |
Notice the pattern? The question isn't "do I enjoy this?" — it's "what breaks if I stop?" If nothing breaks, it's a want. That single question settles most classification arguments.
Starting From Zero Savings? Read This Part Twice
A lot of budgeting advice quietly assumes you already save something. But what if your savings rate is genuinely 0%? First: you're not alone, and you're not broken. A huge number of Indian households live salary-to-salary, especially early in their careers or with single incomes supporting many.
Here's what I'd actually do, in order:
- Track first, judge later. For one month, just record every rupee. Don't try to cut anything yet. Most people discover 2–3 "leaks" they didn't know existed — the daily ₹200 snack run is ₹6,000 a month, and nobody feels it happening.
- Start with 5%, not 20%. On ₹60,000, that's ₹3,000. Small enough that you won't quit, big enough to build the habit. The habit is the product; the amount comes later.
- Pay yourself first. Auto-transfer that 5% on salary day into a separate account. What's left is what you live on. This single trick outperforms every budgeting app ever made.
- Attack one want, not all of them. Pick your biggest painless cut — maybe it's the food delivery habit, maybe an unused gym membership. (Our 15 saving tricks lists the highest-impact small cuts.) One win builds confidence; ten simultaneous cuts build resentment and quitting.
- Scale to 10%, then 15%, then 20%. Raise it with every salary hike: half the hike goes to savings before your lifestyle notices.
How to Actually Track This (Pick One, Stick With It)
Honestly? The best tracking method is the one you'll still be using in three months:
- The notebook: write down daily spending. The physical act of writing makes spending feel real in a way tapping "pay" never does.
- UPI + bank statements: once a month, export statements and categorise spending in a simple sheet. The data is already there — you're just reading it.
- Budgeting apps: several Indian apps auto-categorise SMS transaction alerts. Convenient, but one app used consistently beats five apps tried once.
- Digital envelopes: separate accounts for needs, wants, savings. When the "wants" wallet is empty, the month's fun is over. Brutal, effective.
A Full Sample Monthly Budget (₹60,000 Income)
Let's put it all together — a realistic budget for a single person in a metro, adapted from strict 50/30/20 to something livable. Note this runs slightly over on needs (rent is rent) and compensates elsewhere:
| Category | Item | Amount (₹) | % of income |
|---|---|---|---|
| Needs | Rent (shared 2BHK) | 12,000 | 52% |
| Groceries + cooking gas | 7,000 | ||
| Utilities, phone, internet | 2,500 | ||
| Commute | 3,000 | ||
| Money sent to parents | 5,000 | ||
| Term insurance (monthly share) | 1,500 | ||
| Wants | Eating out / food delivery | 4,000 | 28% |
| Shopping, clothes | 4,000 | ||
| OTT, subscriptions, outings | 3,500 | ||
| Personal care, misc | 2,500 | ||
| Festival sinking fund (Diwali etc.) | 3,000 | ||
| Savings | Emergency fund | 4,000 | 20% |
| Equity SIP | 5,000 | ||
| PPF | 3,000 | ||
| Total | 60,000 | 100% | |
See what happened? Needs crept to 52% because of rent and family support, wants trimmed to 28% to compensate, savings held at 20%. That's the rule working as intended — not as a rigid formula, but as a framework that forces honest trade-offs. Every rupee has a job and a reason.
Frequently Asked Questions
Should the percentages be based on CTC or in-hand salary?
Always in-hand — the money that actually reaches your account. CTC includes PF contributions, gratuity and other amounts you never see monthly. Budgeting on CTC means planning with money you don't have.
Where do SIPs go — savings or investments?
Savings, in this framework. The 20% bucket covers everything that builds your future: emergency fund, SIPs, PPF, NPS, ELSS, and extra debt payments. "Savings" here means "money your future self gets," not just a savings account.
My rent alone is 45% of my income. Is the rule broken for me?
The rule isn't broken; your housing cost is just high relative to income — extremely common in Mumbai, Delhi and Bengaluru. Options: share accommodation, move farther out, or temporarily accept a 60/25/15 split while working to raise income. The rule's job is to make the trade-off visible, not to shame you.
Does the rule work for irregular freelancer income?
With a tweak: budget on your average monthly income over the last 6–12 months, and in good months, push the surplus into savings rather than inflating wants. Freelancers should also aim for a bigger emergency buffer since income is unpredictable.
Should couples combine incomes for 50/30/20?
It usually works better combined — one household, one budget. Pool the in-hand incomes, apply the percentages to the total, and agree together on the wants spending. Separate "fun money" allowances within the wants bucket prevent most arguments.
Is 20% savings enough for retirement?
It's a solid starting point, and far better than 0%. But run the numbers for your own goals as income grows — many financial planners suggest pushing toward 25–30% once you're settled. Starting early matters more than the exact percentage, thanks to compounding. Remember that market-linked investments carry risk and past performance does not guarantee future returns.
Key Takeaways
- 50/30/20 splits in-hand income into needs, wants, and savings — simple enough to actually follow.
- Always calculate on in-hand salary, never CTC.
- Indian realities (metro rent, EMIs, family support) mean your split might be 60/25/15 — adapt, don't abandon.
- Minimum loan EMIs are needs; extra repayments count as savings.
- Starting from 0%? Begin with 5%, automate it, and scale up with each raise.
- Track spending for one month before changing anything — awareness beats willpower.
- Clear high-interest debt before building investments; the maths is unforgiving.
One Last Thing
I'll be straight with you: no budgeting rule will make you rich, and 50/30/20 won't fix an income that's simply too low for your city's costs. What it does — and this is genuinely valuable — is replace money anxiety with money clarity. When you know that ₹12,000 is going to your future every single month, the ₹4,000 dinner with friends stops feeling guilty and starts feeling earned. That's the real product here: not a spreadsheet, but a calmer relationship with your own salary. Start this month. Imperfectly. You'll refine it as you go.
Disclaimer: This budgeting framework is for education, not personalised financial advice — adapt the percentages to your own income and obligations. CashCrafty and the author are not SEBI-registered investment advisers.
Continue Reading
A plain-English guide to credit cards in India — the genuine perks, the genuinely nasty traps like the minimum-due cycle, and five golden rules to use one without getting burned.
From your first demat account to your first share: a beginner's walkthrough of the Indian stock market, with the rules and mistakes that actually matter.
An emergency fund is money set aside for life's surprises — job loss, medical bills, urgent repairs. This guide shows you how much to save, where to keep it, and how to build it step by step.